FLEXIBLE BUSINESS FUNDING
Business Line of Credit
Flexible access to business funds when needs arise.
A business line of credit may provide revolving access to funds up to an approved limit. Draw funds when needed, repay the outstanding balance, and potentially access available credit again, subject to provider terms.
One Short Request
No Obligation
No Hard Credit Pull to Start
Credit limits, pricing, fees, repayment requirements, and availability vary by provider.
Revolving Access
Draw from an approved limit as business needs arise.
Use What You Need
You may draw only a portion of the available credit.
Potential Reuse
Available credit may replenish as balances are repaid.
Terms Vary
Costs, draw rules, renewals, and repayment vary by provider.
UNDERSTANDING THE PRODUCT
What Is a Business Line of Credit?
A business line of credit is a financing structure that may provide access to funds up to an approved credit limit.
Instead of receiving the entire approved amount at once, the business may draw only what it needs. Pricing is generally connected to the amount used, although account fees, draw fees, minimum charges, or other costs may apply.
As an outstanding balance is repaid, some or all of the available credit may be restored. Draw periods, payment frequency, renewals, and continued access depend on the provider’s agreement and ongoing eligibility.
At a Glance
Structure: Revolving access up to an approved limit
Common fit: Recurring, short-term, or unpredictable business needs
Cost basis: Often connected to the amount drawn, plus applicable fees
Availability: Subject to account status, renewal, and continued eligibility
Common Uses for a Business Line of Credit
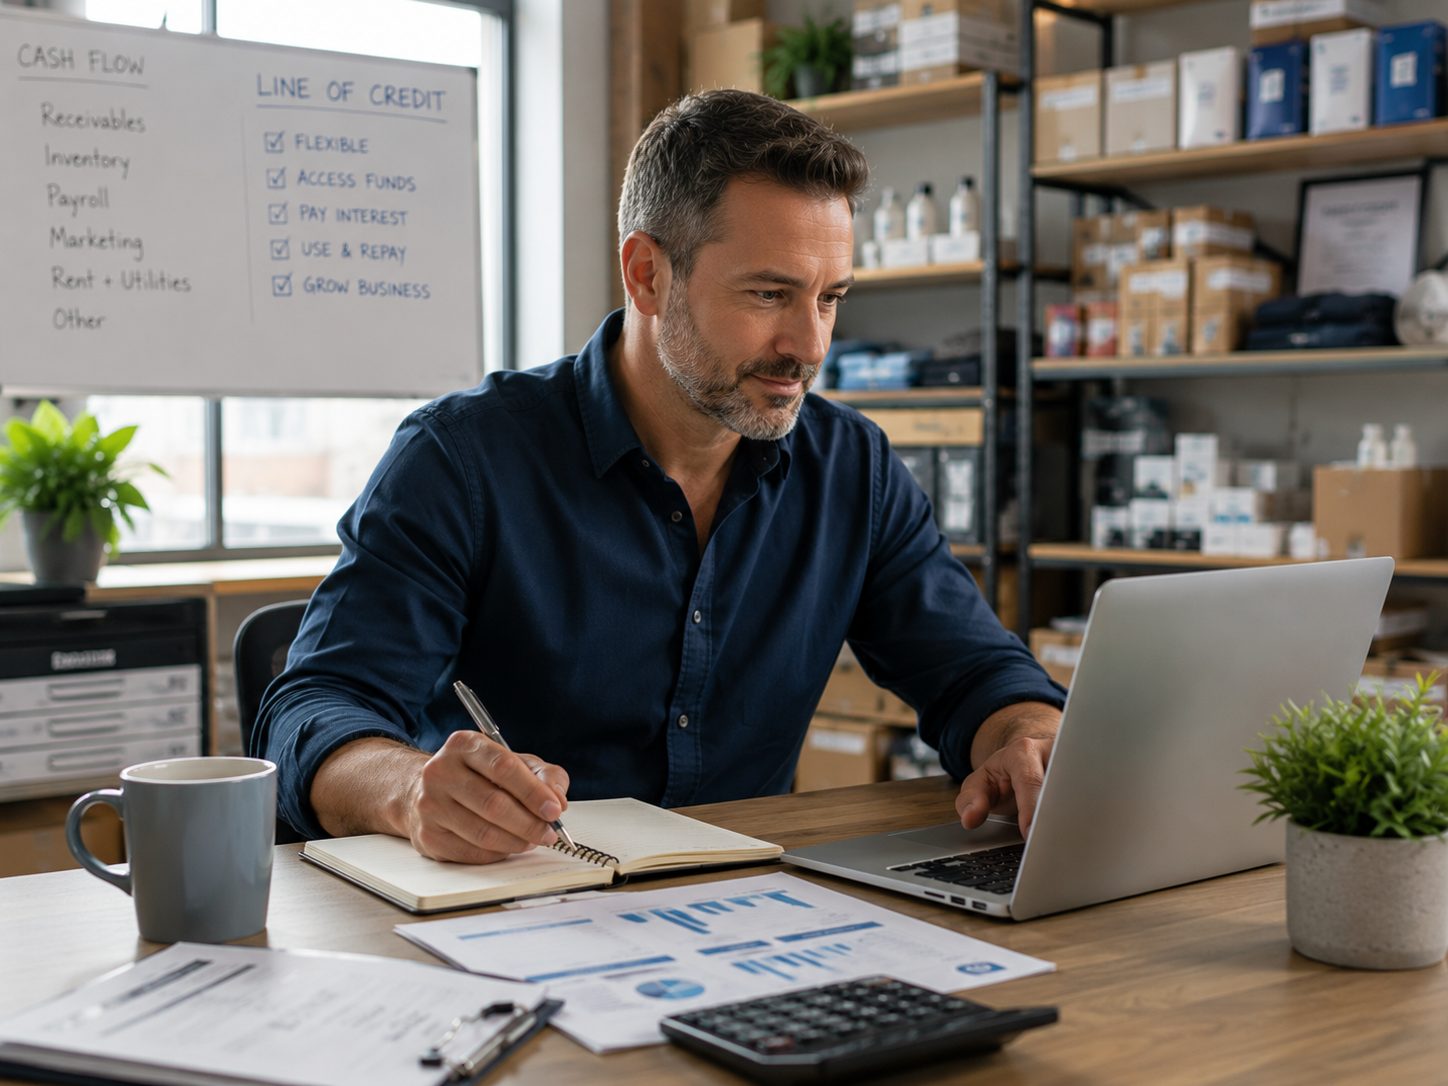
Businesses may use a line of credit for eligible short-term and recurring operating needs, subject to the provider’s agreement.
Cash-Flow Gaps
Help cover operating expenses while waiting for customer payments or receivables.
Inventory and Suppliers
Purchase inventory, pay suppliers, or prepare for upcoming customer demand.
Seasonal Needs
Support payroll, marketing, supplies, or temporary expenses during seasonal changes.
Unexpected Expenses
Address repairs, replacements, or time-sensitive business opportunities.
Could a Line of Credit Fit Your Business?
The appropriate structure depends on your funding purpose, timing, repayment preferences, qualifications, and the options available.
A Line of Credit May Be Worth Exploring When:
- Your business has recurring short-term expenses
- Cash-flow needs change from month to month
- You want access without taking the full amount immediately
- You purchase inventory throughout the year
- Your business experiences seasonal fluctuations
- You want funds available for unexpected needs
A Term Loan May Fit Better When:
- You have one clearly defined purchase or project
- You know the full amount needed at the beginning
- You prefer a defined repayment schedule
- The funding supports a longer-term investment
- You do not need recurring access after repayment
A SIMPLE STARTING POINT
How to Explore Line-of-Credit Options
The initial VeriPoint request is designed to be straightforward and does not require document uploads.
1
Submit an Initial Request
Provide basic information about your business, the amount you are exploring, and the intended use of funds.
2
Funding Partner Review
Your request may be routed to participating funding partners whose programs could align with the information submitted.
3
Review Potential Terms
If an option may be available, review the limit, draw rules, repayment structure, pricing, fees, and requirements.
4
Choose Your Next Step
You decide whether to continue. There is no obligation to accept an offer or open an account.
Important Terms to Review
Before accepting any funding arrangement, review the complete agreement and ask the provider questions about costs, access, and repayment.
Costs and Fees
Review interest or financing charges, draw fees, account fees, minimum charges, and opening, maintenance, or renewal costs.
Repayment and Access
Confirm payment frequency, minimum draws, the draw period, renewal terms, and when available credit may be reduced or suspended.
Guarantees and Collateral
Depending on the provider and amount, a personal guarantee, business assets, a lien, or other security may be required.
Frequently Asked Questions
How much could I access through a business line of credit?
Potential credit limits depend on the provider, business revenue, credit history, time in business, bank activity, existing obligations, requested amount, and other qualifications. The approved limit may differ from the amount requested.
Do I pay interest on the full credit limit?
Pricing is generally connected to the amount drawn rather than the full approved limit. Maintenance fees, draw fees, minimum charges, or other costs may still apply. Review the complete pricing terms before proceeding.
Can I use the line of credit more than once?
A revolving line of credit may allow funds to become available again as an outstanding balance is repaid. Continued access depends on the provider’s terms, account status, renewal requirements, and ongoing eligibility.
Will submitting a request affect my credit?
The initial VeriPoint Funding request does not require a hard credit pull to start. A participating funding partner may request authorization to review your credit later if you choose to continue.
Is collateral required?
Some business lines of credit may be unsecured, while others may require business assets, a lien, or other collateral. A personal guarantee may also be required.
Am I required to use or accept the available credit?
No offer must be accepted. If an account is opened, requirements vary by provider. Some accounts may have minimum draw requirements, annual fees, inactivity fees, or other conditions even when funds are not being used.
Ready to Explore Line of Credit Options?
Tell us about your business, the amount of funding you are exploring, and how you intend to use the funds.
Takes about one minute · No obligation · No hard credit pull to start
No obligation to accept an offer.
VeriPoint Funding does not guarantee approval, funding availability, a particular credit limit, or specific terms. Business lines of credit are subject to funding partner and/or lender approval and may not be available in all states or industries. Rates, fees, draw requirements, repayment terms, collateral requirements, documentation requirements, and timing vary by provider and applicant qualifications. VeriPoint Funding is not a direct lender and does not make credit decisions.